If you are researching a strathmore second mortgage, here is what matters most before you apply.
Strathmore Second Mortgage at a Glance
- Lets you access home equity without touching your existing low-rate first mortgage
- Approval depends on combined loan-to-value, property type, and your exit strategy
- Property type and location can affect your rate as much as your credit profile
- Funding is typically faster than refinancing through a bank
- Best suited to short- to medium-term needs with a clear repayment plan
Strathmore Second Mortgage: What to Know
If you own property in Strathmore and need to access equity, you may wonder whether your rate will be higher simply because you are outside Calgary.
Usually, no. The town boundary itself is not the main pricing factor.
What matters is the risk profile of the property and the loan: its value, your existing mortgage, the combined loan-to-value, resaleability, property type, and your plan for repaying the second mortgage.
That distinction matters in Strathmore. A newer detached home in town may look very similar to a comparable Calgary property from a lender’s perspective. An irrigated quarter-section or ranch property outside town is a completely different asset.
Strathmore is not just “Calgary, but farther east”
Strathmore is a community of roughly 14,000 people about 40 minutes east of Calgary along Highway 1. It serves as an agricultural centre for surrounding Wheatland County and the irrigation-district farmland nearby.
The local property mix includes:
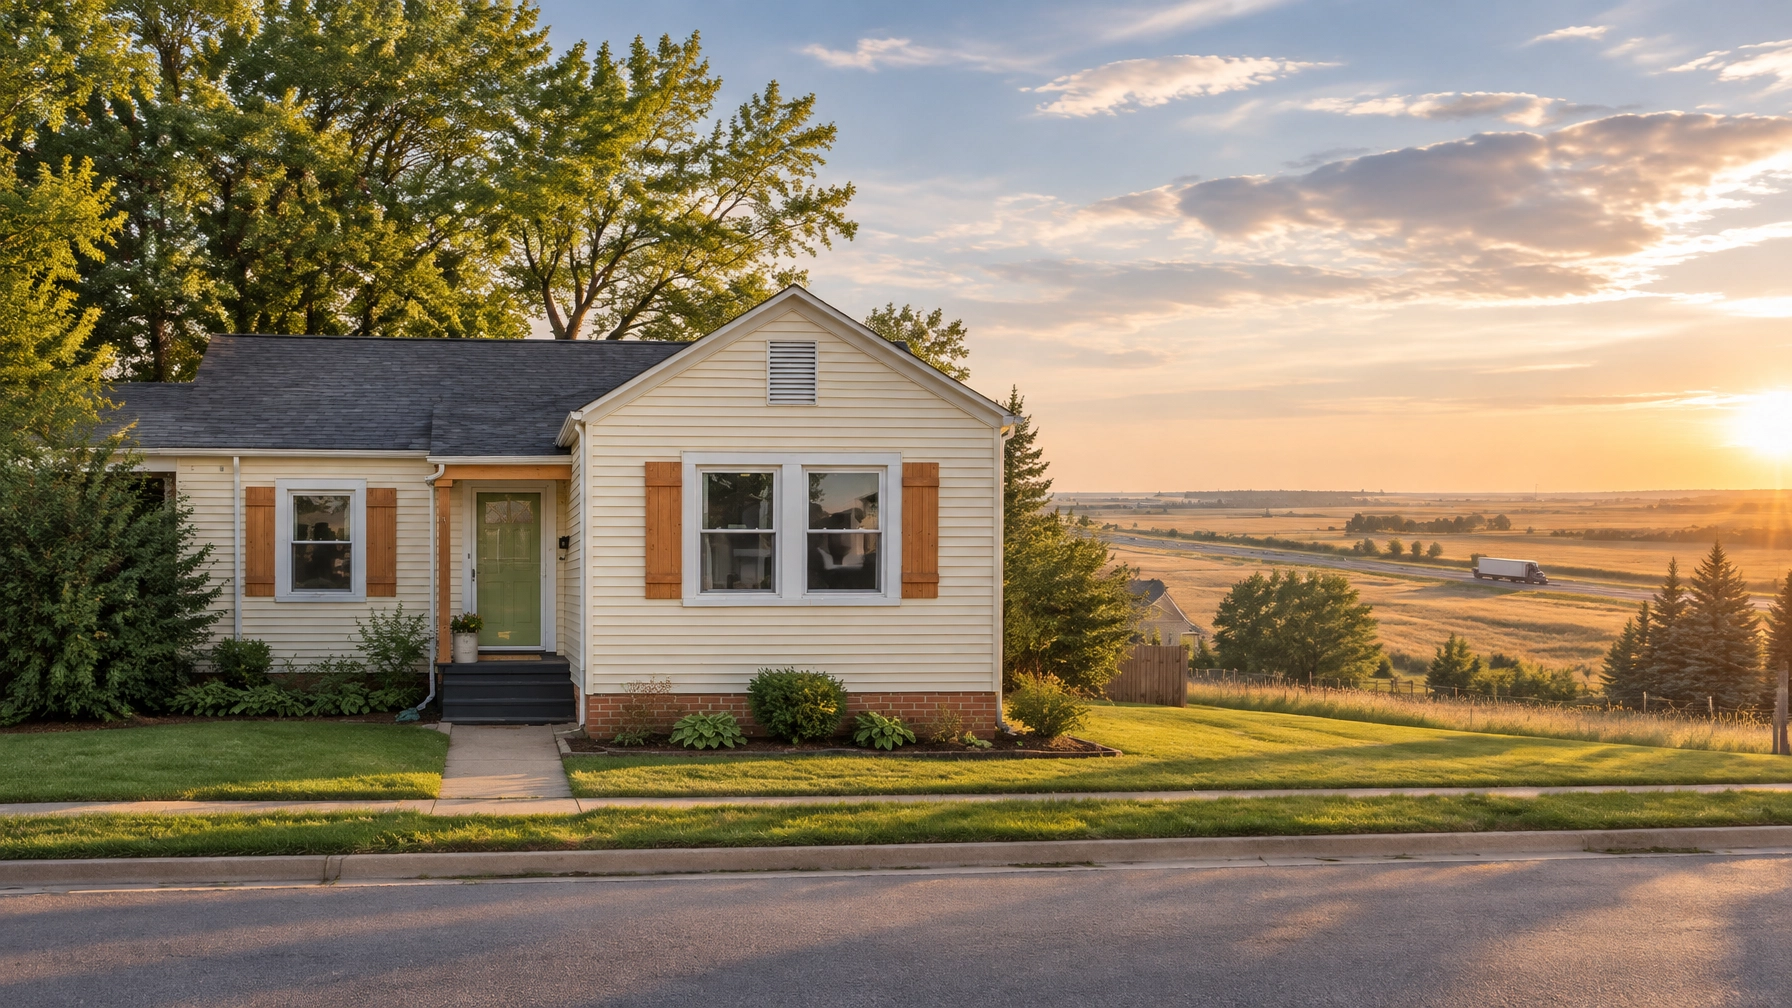
- Older, modest in-town homes
- Newer subdivision construction
- Homes owned by Calgary commuters
- Acreages and hobby farms
- Irrigated cropland
- Ranch properties and agricultural operations
That creates a wider range of mortgage files than you might see in a typical Calgary suburb.
A $340,000 in-town house, a $2.5 million quarter-section, and a $450,000 Calgary suburban home should not receive the same pricing simply because they are all “Alberta real estate.”
What actually drives a second mortgage rate?
A second mortgage sits behind your existing first mortgage. If the property ever had to be sold, the first lender gets paid before the second lender. That extra risk is why second mortgage rates are generally higher than first mortgage rates.
Your rate and available amount will usually depend on:
- Loan-to-value and combined LTV
- Property type, condition, and location
- Appraised value and resaleability
- Whether the property produces agricultural income
- Your first mortgage balance and interest rate
- Credit events, income history, and overall borrower situation
- The purpose of the funds
- Your exit strategy
A standard home with good resale demand may give a lender more comfort than a specialized agricultural property. That is not necessarily a judgment about Strathmore. It is a judgment about how easily the asset could be sold if the plan went sideways.
Side-by-side: three very different Alberta files
The following examples are illustrative only. Actual rates, fees, LTV limits, and approval amounts depend on the complete application and lender commitment.
| Borrower and property | Main lending considerations | Possible combined LTV approach | What may affect pricing |
|---|---|---|---|
| Strathmore in-town home: $340,000 | Modest residential value, ordinary resale market, existing first mortgage | Often assessed around a residential lender’s maximum, such as 70%–75% | Available equity, home condition, first mortgage, credit, and requested amount |
| Calgary suburban home: $450,000 | Standard residential property with a larger and more liquid resale market | Often assessed around 70%–75%, depending on the lender | LTV, neighbourhood, income, credit, and exit plan |
| Strathmore quarter-section: $2.5 million | Agricultural land, improvements, operating debt, equipment, land/building value split | May be materially lower than a standard residential maximum | Agricultural use, appraisal quality, land liquidity, debt structure, and operating cash flow |
The Calgary borrower may have more lender options because a typical suburban home is familiar and relatively easy to resell.
The Strathmore homeowner with a standard in-town property may still receive competitive private lending terms if the equity and exit strategy are strong.
The quarter-section may have substantial equity, but that does not automatically make it a simple or inexpensive second mortgage.
Why agricultural property is priced differently
Agricultural financing in Alberta requires a closer look than a standard home equity loan.
An irrigated quarter-section may include:
- Valuable land
- A residence
- Shops, barns, grain bins, or other improvements
- Irrigation infrastructure
- Equipment
- Crop or livestock operations
- Operating loans and other secured debt
The appraisal must separate the value of the land from the value of the buildings and improvements. The lender also needs to understand whether the property is income-producing and how the operation affects the borrower’s ability to repay.
A lender may ask for more documentation on a farming file, including 12 months of bank statements for commercial or farm applications. The review may also involve tax information, mortgage statements, property tax details, and existing registered debts.
That is why a private lender may offer a lower LTV or higher rate on agricultural land than on a Calgary house, even when the farm property is worth much more.
For farmers and landowners, private lenders in Alberta can provide a useful bridge when a conventional lender cannot move quickly or does not fit the property. The key is to structure the loan around a realistic repayment plan rather than treating farm equity as an unlimited cash machine.
Worked example: a $340,000 Strathmore home
Suppose a homeowner owns an in-town Strathmore property appraised at $340,000.
Assume:
- Existing first mortgage: $210,000
- Maximum combined LTV used for illustration: 75%
- Maximum total registered financing: $255,000
- Potential gross second mortgage: $45,000
Now subtract estimated costs:
- Lender or brokerage fee at 3%: $1,350
- Legal fees: $1,500
- Appraisal: $500
- Estimated net proceeds: approximately $41,650
At an illustrative interest-only rate of 12.99%, the monthly interest on $45,000 would be about $487. The actual payment structure may differ, and some lenders may require interest reserves, scheduled payments, or a specific term.
The important point is the amount of usable equity. A $340,000 property can provide meaningful funds, but it may not support a large loan after the first mortgage and closing costs are deducted.
That creates a practical floor. If you only need $10,000 or $15,000, a second mortgage may not make sense once legal, appraisal, and lender fees are included.
When keeping your first mortgage beats refinancing
Many Strathmore and Calgary homeowners have a first mortgage at a much lower rate than today’s second mortgage market.
Suppose the Calgary borrower owns a $450,000 home and owes $280,000 on a first mortgage at 2.49%. They need $50,000 for debt consolidation.
One option is refinancing the entire mortgage. That could mean:
- Breaking the existing first mortgage
- Paying a penalty
- Replacing a low-rate mortgage with a higher-rate mortgage
- Paying a higher rate on the entire balance, not just the new funds
A second mortgage may allow the borrower to:
- Keep the 2.49% first mortgage
- Borrow only the $50,000 required
- Avoid disturbing the existing first-mortgage structure
- Consolidate credit cards or other high-cost debt
- Refinance later once the financial situation improves
For example, $50,000 at an illustrative 10.99% interest-only rate costs about $458 per month in interest. Refinancing the full $330,000 at a higher rate could cost more overall, even though the second mortgage has a higher rate, because the higher rate applies only to the smaller second loan.
This strategy is not automatically better. A second mortgage can be more expensive over a long period, especially if it renews repeatedly. It works best when there is a clear exit, such as:
- Selling another asset
- Receiving business or farm proceeds
- Rebuilding credit
- Increasing documented income
- Refinancing into a lower-cost first or B mortgage
- Selling the property within a defined timeframe
When a second mortgage is the wrong move
A second mortgage is not a magic reset button. It may be the wrong choice if:
- You have no realistic way to make the payments
- The requested amount is too small to justify the fees
- You are borrowing to cover an ongoing monthly deficit
- The property has little remaining equity
- The appraisal value is uncertain
- You are using new debt to delay an unavoidable sale
- The loan has no clear repayment or refinance plan
Homeowners should also compare a second mortgage with other options. Depending on the situation, that could include a conventional refinance, secured line of credit, debt settlement, sale of an asset, or a structured family arrangement.
The right product depends on the problem. A bad credit mortgage in Calgary may be appropriate for a homeowner with equity and a temporary credit event. A mortgage for a divorce settlement may require speed and a clean payout structure. A senior homeowner may want to explore a reverse mortgage in Edmonton or Alberta rather than adding regular monthly payments.
Different problem, different tool.
How NOW Mortgage reviews a Strathmore application
NOW Mortgage starts with the property and the objective, not just a credit score.
The process typically includes:
- Initial conversation , no credit check is required to discuss your options.
- Equity and property review , including the first mortgage, property type, and estimated value.
- Upfront cost estimate , rates, lender fees, legal costs, and appraisal expenses are explained before you commit.
- Application and documentation , requirements vary between residential, commercial, and farm files.
- Independent appraisal , arranged to confirm market value.
- Lender review and commitment , the proposed amount, rate, term, and conditions are reviewed with you before signing.
For more detail, see the NOW Mortgage process or start a secure application.
Strathmore second mortgage FAQ
Is a second mortgage in Strathmore more expensive than one in Calgary?+
Not automatically. A standard Strathmore home may receive similar pricing to a comparable Calgary home. Agricultural land, acreages, unusual properties, and smaller-market assets may receive different pricing because they have different risk and resale characteristics.
Can I get a second mortgage on a farm near Strathmore?+
Possibly. The lender will likely review the land, buildings, improvements, existing debt, operating income, and appraisal carefully. Farm files may require more documentation than residential files.
How much equity do I need?+
It depends on the property type and lender. A common starting point is to calculate the potential combined LTV, then subtract the existing first mortgage and closing costs. Agricultural properties may have lower workable LTV limits.
Can I keep my low-rate first mortgage?+
Often, yes. That is one of the main reasons borrowers consider a second mortgage instead of refinancing. The second mortgage can leave the existing first mortgage untouched, but the total cost and exit plan should be compared carefully.
Can I apply with bruised credit?+
Private lending is primarily equity-based, so a low score, consumer proposal, collections, or past bankruptcy may not automatically end the conversation. You can learn more about bruised credit mortgage options.
Is a second mortgage the same as a home equity loan?+
They are related, but the structure varies. A second mortgage is registered behind the first mortgage. A home equity loan may refer more generally to borrowing against available equity. Review the registration, fees, payment terms, and renewal conditions before signing.
The short answer
Location can influence a second mortgage, but the municipal boundary is not the rate.
A newer Strathmore home may price much like a Calgary home. A $2.5 million irrigated quarter-section is a different lending file because the lender is assessing land, improvements, farm income, operating debt, and resaleability.
The best comparison is not “Strathmore versus Calgary.” It is:
What is the property, how much equity is available, what is the money for, and how will the loan be repaid?
That is the information a lender needs to provide a useful answer: and a transparent cost estimate.