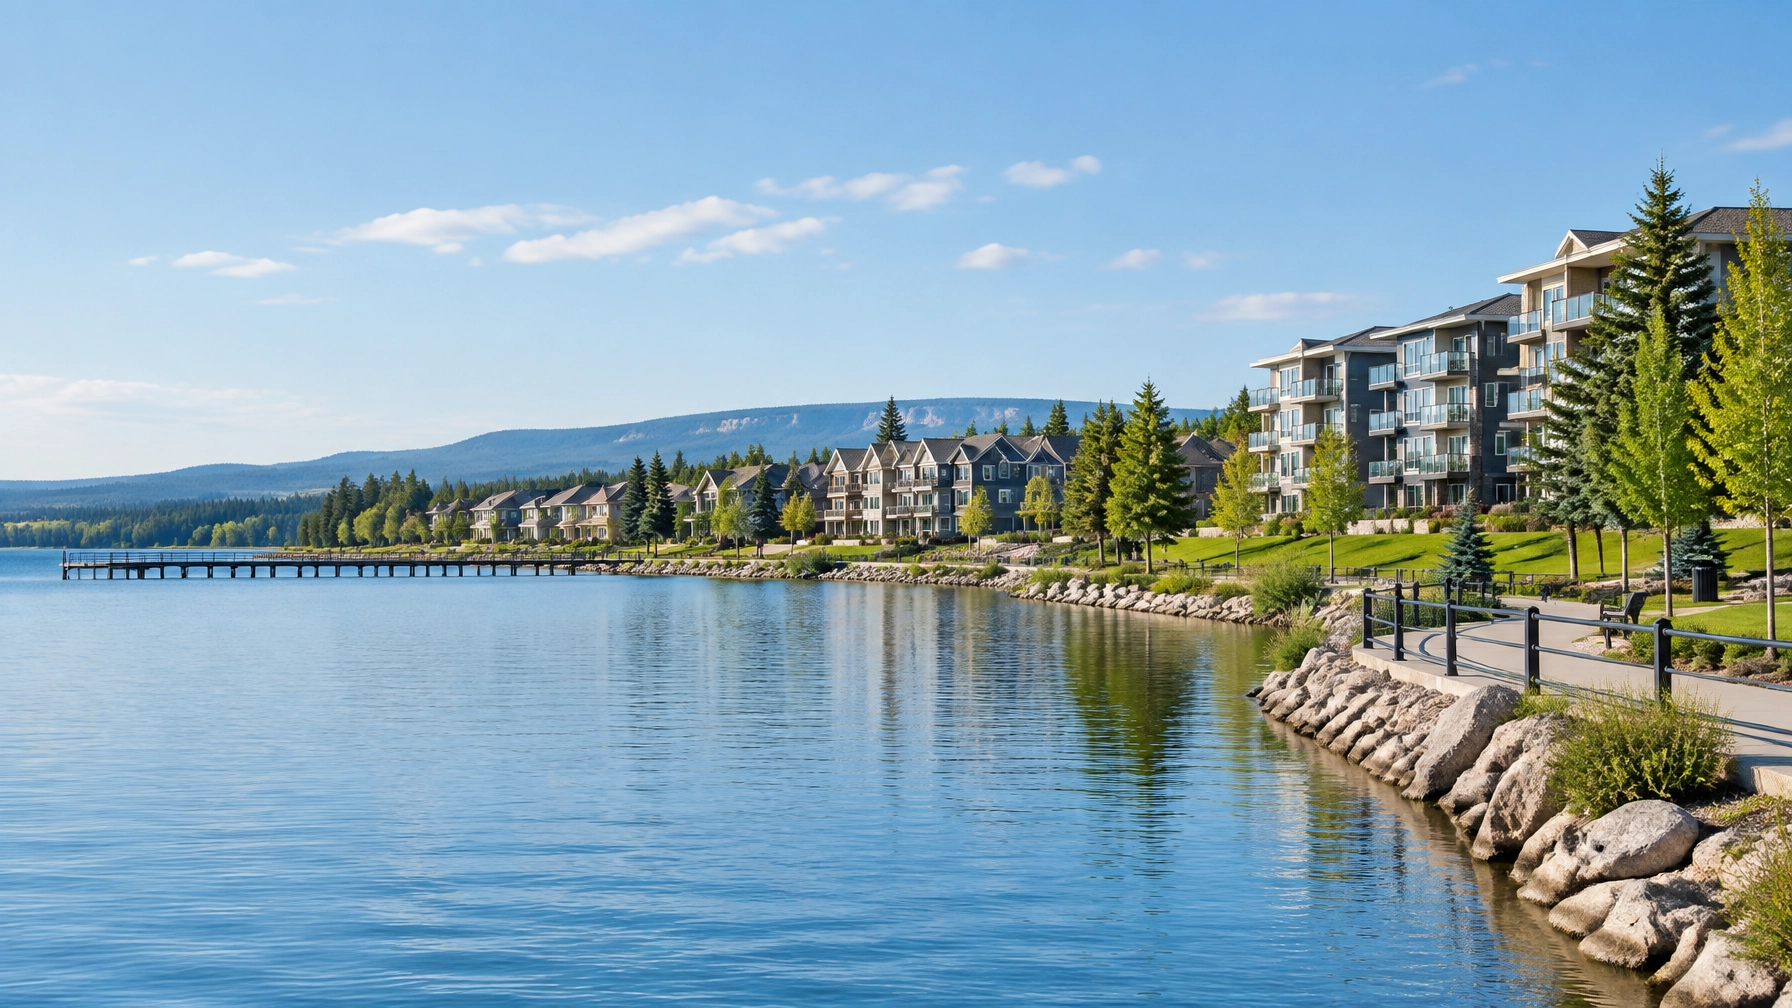
Sylvan Lake is not just another Alberta housing market.
It is a year-round community of roughly 16,000 people, about 25 minutes west of Red Deer, with a summer population that can feel several times larger once visitors, seasonal owners, boaters, and vacation renters arrive.
That creates a local mortgage challenge: the property may be valuable, but a traditional lender may not know what to do with it.
A bank may decline a lake-area condo because of its building, use, or rental profile. It may discount hospitality income because it fluctuates seasonally. It may treat an acreage near Red Deer County differently from a standard suburban home.
When that happens, a private mortgage in Sylvan Lake can provide a short-term bridge, but it needs to be structured carefully.
Why banks decline Sylvan Lake properties
Sylvan Lake has a unique mix of:
- Permanent detached homes
- Seasonal and recreational properties
- Lake-area condominiums
- Townhouse developments
- Short-term vacation rentals
- Investment and second-home properties
- Acreages and farm properties around Red Deer County
- Owners who commute to Red Deer or work in tourism, hospitality, oilfield services, and recreation
That mix is attractive to buyers and visitors. It can be less attractive to a bank’s underwriting department.
Banks generally prefer straightforward collateral, stable employment income, predictable occupancy, and property types that fit standardized lending rules.
A Sylvan Lake property can fall outside those rules for several reasons:
- It is used mainly as a seasonal or recreational home
- It is marketed as a vacation rental or tourist accommodation
- The condominium corporation has restrictions, weak financials, or insurance concerns
- The building is newer, unusual, or difficult for an insurer to classify
- The borrower’s income changes significantly between summer and winter
- The owner is self-employed or relies on contract, commission, or hospitality income
- The property is rural, has acreage, or includes agricultural land
- The borrower needs money quickly for a separation, estate, or debt problem
A bank’s “no” may mean the file does not fit its policy. It does not automatically mean the property has no value.
Recreational and seasonal properties need a different approach
A seasonal condo near the lake is not always treated like a standard owner-occupied home in Red Deer.
Some lenders may require a larger down payment, refuse short-term rental use, or decline the property altogether if it is considered non-conforming security. Winter access, servicing, zoning, parking, condominium documents, and marketability can all matter.
Private lenders can sometimes consider these properties when the equity, location, condition, and exit plan make sense.
That flexibility comes with a trade-off.
Recreational and seasonally used properties are harder to place and are priced accordingly. A private lender may use a lower loan-to-value ratio, charge a higher rate, or require more documentation about the property’s use and future saleability.
At NOW Mortgage, financing may be available up to 75% LTV depending on property type, location, and overall file strength. A lakefront property, vacation rental, townhouse, and rural acreage will not necessarily receive the same terms.
Condo and townhouse financing in Sylvan Lake
Sylvan Lake has a meaningful condominium presence alongside detached homes and newer townhouse development. Statistics Canada data identifies approximately 945 occupied condominium dwellings in the community.
For a standard condo, a bank may be comfortable. For a condo used as a vacation rental, the answer can change quickly.
Lenders may review:
- The condominium corporation’s financial statements
- Reserve fund and insurance information
- Building condition and special assessments
- The percentage of owner-occupied units
- Short-term rental rules
- Whether the unit is legally a residential dwelling or part of a resort-style development
- Recent comparable sales and overall market liquidity
A private mortgage can be useful when the property is sound but does not meet conventional lending criteria. The lender will still want an appraisal and a clear understanding of how the loan will be repaid.

Hospitality income is real, but banks may discount it
A restaurant owner, hotel employee, seasonal operator, or short-term rental host may have strong annual income but uneven monthly deposits.
That can create problems during bank underwriting.
A traditional lender may:
- Average income over several years
- Exclude some short-term rental revenue
- Require extensive tax documentation
- Discount commission, contract, or seasonal earnings
- Apply strict debt-service calculations
Private lenders are generally more focused on the property’s value and available equity. Income still matters, but flexible lending criteria can make it easier to explain a non-traditional income pattern.
This does not mean income is irrelevant or that every application is approved. It means the conversation can include the full picture instead of being reduced to one income line or credit score.
What a private mortgage in Sylvan Lake can help solve
A private mortgage is usually a short-term bridge, not a permanent replacement for a bank mortgage.
Common uses include:
Debt consolidation
If credit cards, tax balances, vehicle loans, or unsecured debts are creating expensive monthly payments, a home equity loan in Alberta may consolidate those debts into one mortgage-secured obligation.
The goal should be more than moving debt around. A responsible plan also addresses how the debt will be prevented from rebuilding.
Divorce or separation buyouts
A separation may require one spouse to refinance, remove the other person from title, or buy out their equity in the family home.
A mortgage for divorce settlement can provide interim financing while income, support payments, and legal agreements are being finalized.
See NOW Mortgage’s divorce and separation financing options.
Estate settlements
Heirs may need funds to pay taxes, equalize inheritances, complete repairs, or buy out another beneficiary before selling the property.
A private loan can create time to sell properly instead of accepting the first offer under pressure.
Agricultural and acreage financing
Properties around Red Deer County, Eckville, and Bentley may include farm buildings, raw land, acreage homes, or mixed agricultural use.
These properties need specialized analysis. NOW Mortgage’s agricultural financing program notes lending of up to 55% LTV in many cases, with higher leverage considered only in exceptional situations.
Reverse mortgages for local seniors
Some Sylvan Lake homeowners have substantial equity but limited retirement income. A reverse mortgage may help with cash flow, debt repayment, home repairs, or aging in place.
A reverse mortgage is not free money: interest is added to the balance, and the loan is generally repaid when the home is sold or the borrower moves out permanently. Read common reverse mortgage questions before deciding.
What the bank timeline looks like versus private lending
Every file is different, but the general process often looks like this:
| Stage | Traditional bank | Private lender |
|---|---|---|
| Initial review | Several days to weeks | Often same day or within a few days |
| Income verification | Detailed and standardized | More flexible, depending on equity |
| Property review | Strict policy and insurer criteria | Case-by-case property assessment |
| Approval | May require multiple conditions | Often faster once documents are complete |
| Funding | Commonly several weeks | Potentially days to a couple of weeks |
| Main focus | Income, credit, debt ratios, policy | Equity, property value, risk, exit strategy |
Speed is useful, but it should not replace due diligence. You still need an appraisal, legal review, written terms, and a realistic plan to repay the loan.
What does a private mortgage cost?
Private mortgage rates are higher than bank rates. That is the price of flexibility, speed, and accepting properties or borrower situations that conventional lenders may reject.
Your total cost may include:
- Interest
- Lender fee
- Broker fee, if applicable
- Legal costs
- Appraisal fee
- Administration or renewal fees
- Discharge or prepayment charges
NOW Mortgage’s approach is to provide upfront cost estimates, including fees, before you commit. Do not compare offers using the interest rate alone.
The right question is: What will this financing cost from funding to repayment, and does the plan still work if the property takes longer to sell or refinance?
The exit strategy matters more than the approval
A private mortgage should have a clear destination.
Your exit may be:
- Refinancing with a bank after improving credit
- Requalifying after showing more stable income
- Paying down consumer debt
- Selling a seasonal or investment property
- Completing a divorce or estate settlement
- Moving from private financing to a credit union
- Using proceeds from a business or asset sale
Before accepting an offer, ask what happens if the Sylvan Lake market softens, a buyer’s financing fails, or your refinance is delayed.
A good short-term loan gives you time. A poorly planned loan simply moves the deadline closer.
No credit check to get started
NOW Mortgage does not require a credit check to start and review your options.
That means you can begin by discussing the property, current mortgage, estimated value, income, and purpose of the funds. It does not mean every application is approved without reviewing the file. Property value, equity, title, legal issues, and repayment strategy still matter.
You can start with the NOW Mortgage pre-qualification process.
Sylvan Lake private mortgage FAQ
Can I get a private mortgage on a seasonal property?
Possibly. Seasonal properties are assessed more conservatively than standard homes. The lender may consider use, location, access, condition, appraisal value, and available equity.
Can short-term rental income help me qualify?
It may help explain the property’s financial picture, but it may not be treated the same way as stable employment income. Provide booking history, tax records, operating costs, and proof that the use is permitted.
What if I own a lake property but live elsewhere?
A second property can still be used as security. The lender will review the existing mortgage, property value, occupancy, rental use, and your plan for repayment.
Can I borrow up to 75% of my Sylvan Lake property’s value?
Up to 75% LTV may be possible depending on the property type and file strength. Recreational, rural, resort-style, and short-term rental properties may receive lower maximum LTVs.
Is a private mortgage the same as a bad credit mortgage in Calgary?
Not exactly. A private mortgage can help someone with damaged credit, but it may also be used by someone with good credit whose property, income, timing, or life event does not fit a bank’s rules. The same applies to searches for a private mortgage Edmonton, private lenders Alberta, or a second mortgage Calgary, the location is only one part of the underwriting decision.
What should I bring to the first conversation?
Useful information includes:
- Property address and type
- Estimated value
- Current mortgage balance
- Any second mortgages or liens
- Intended use of the property
- Income and employment details
- Amount needed
- Desired timeline
- Your proposed exit strategy
The bottom line
Sylvan Lake’s mix of tourism, seasonal ownership, condominiums, townhouses, detached homes, and surrounding acreages creates financing opportunities, but also lending complications.
If a bank says no, a private mortgage may help you access equity, consolidate debt, complete a separation or estate settlement, finance an acreage, or keep a property while you work toward a conventional refinance.
Just remember: it is usually a short-term solution with a higher cost.
The strongest application is not simply the one with the most equity. It is the one with transparent costs, realistic terms, and a clear path back to traditional financing.
For a confidential review, contact NOW Mortgage or begin with no-credit-check-required options through the online application.
Leave a Reply