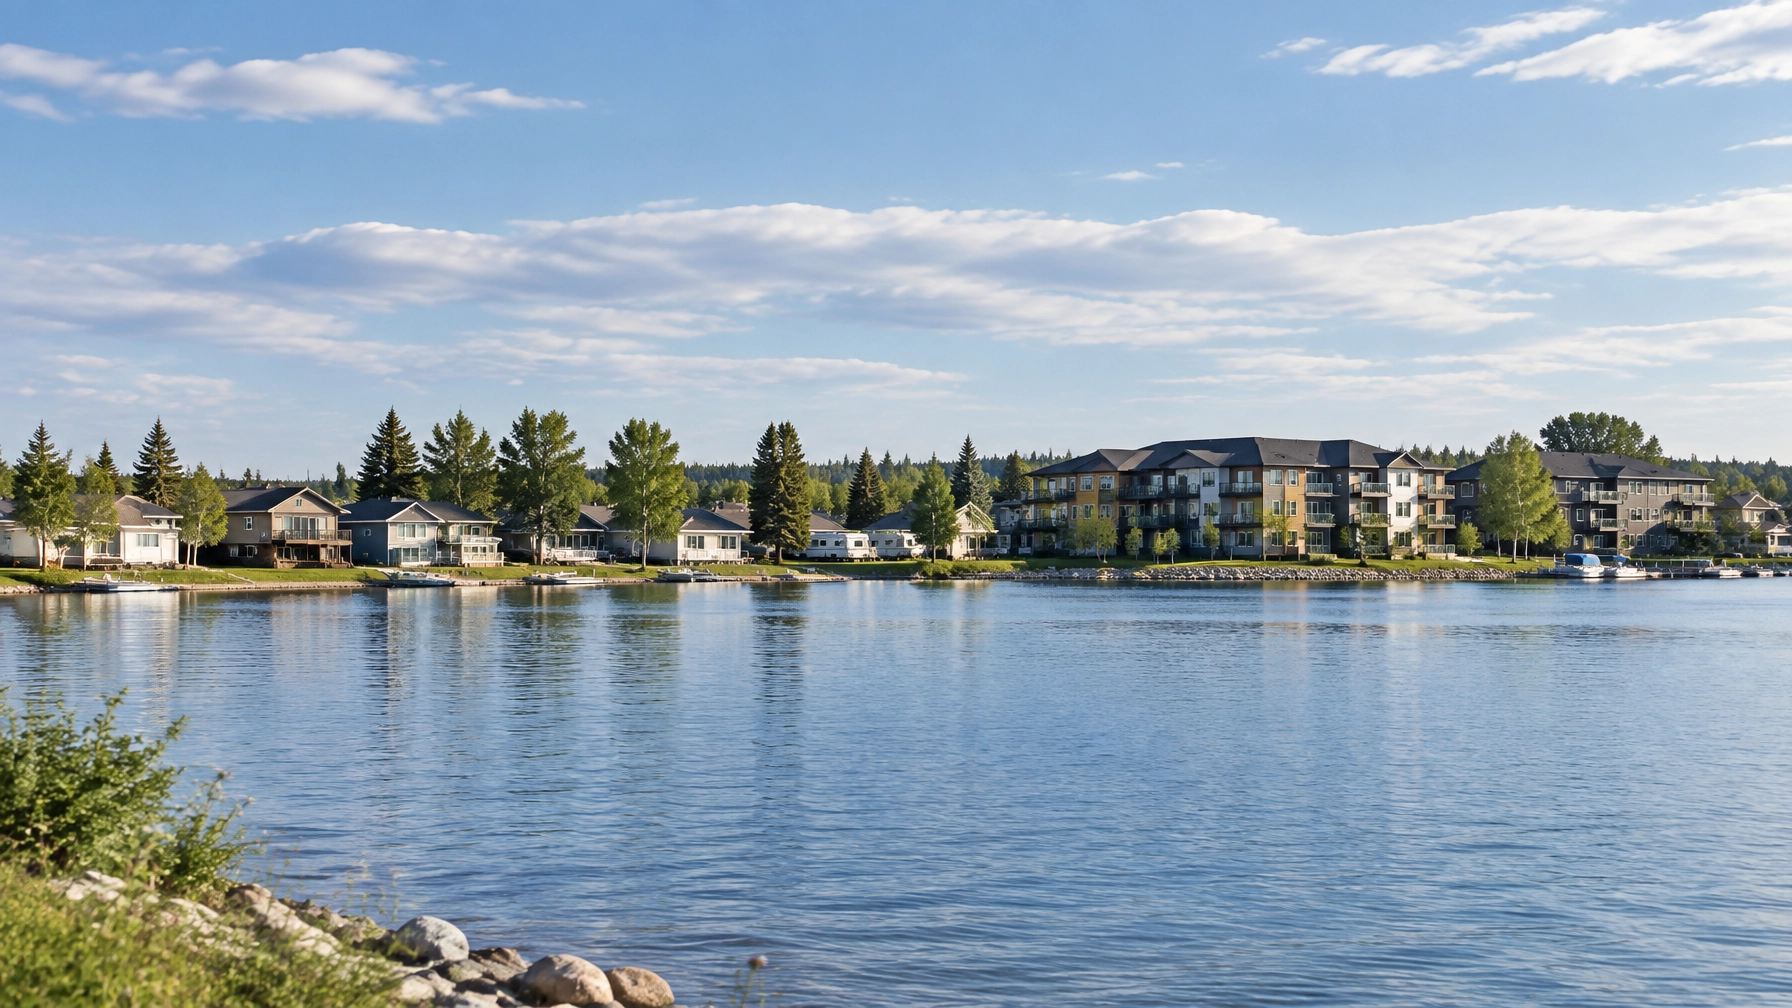
If you are comparing a second mortgage in Sylvan Lake with one in Calgary, it is easy to assume the town boundary determines the rate.
It does not: not by itself.
The bigger question is what the property actually is. A year-round in-town home, a lakefront recreational property, a condo used as a short-term rental, and an acreage near Bentley may all receive very different treatment from lenders.
In Sylvan Lake, property type, resaleability, use, and combined loan-to-value often matter more than the difference between Sylvan Lake and Calgary.
Sylvan Lake is not one single mortgage market
Sylvan Lake is a town of roughly 16,000 permanent residents near Red Deer, but its real estate market is much busier and more varied than that number suggests.
The lake attracts substantial seasonal traffic, with tourism and recreation playing a major role in the local economy. The housing stock includes:
- Permanent detached homes in established neighbourhoods
- Newer condos and townhouses
- Lakefront and near-lake recreational properties
- Short-term rental units
- Seasonal homes and cottages
- Acreages in the surrounding Red Deer County area
- Properties connected to nearby communities such as Eckville and Bentley
The Town of Sylvan Lake and Statistics Canada census data provide useful context on the community’s growth and housing stock.
That variety is good for homeowners: but it means lenders do not treat every Sylvan Lake property the same way.
What actually determines a second-mortgage rate?
A second mortgage is registered behind your first mortgage. The lender is taking second position, so pricing reflects the amount of equity available and the difficulty of recovering that money if the property has to be sold.
The main factors are:
1. Combined loan-to-value
The combined loan-to-value, or CLTV, is calculated as:
First mortgage balance + second mortgage ÷ appraised property value
For example:
- Property value: $420,000
- First mortgage: $220,000
- Proposed second mortgage: $60,000
- Total financing: $280,000
- Combined LTV: 66.7%
Lower CLTV generally means better pricing and more lender options. Many private lenders in Alberta consider files up to roughly 75% combined LTV, depending on the property and borrower. Some may go higher in select situations, while condos, rural properties, and recreational homes may be capped lower.
2. Property type and resaleability
A standard, year-round detached home is usually easier to value and resell than a seasonal lakefront property with unusual construction or limited services.
That difference affects:
- Maximum available financing
- Interest rate
- Lender fees
- Appraisal requirements
- The number of lenders willing to review the file
3. Primary residence versus seasonal use
A home occupied year-round as your primary residence is usually easier to place than a cottage used several months a year.
Lenders may ask about:
- Year-round road access
- Heating and plumbing
- Municipal servicing
- Winterization
- Insurance availability
- Whether the property is legally suitable for its current use
A lakefront property with no year-round municipal servicing: or one whose value depends heavily on a seasonal premium: may be treated as specialty real estate.

4. Condo documentation and building risk
Condos are common in Sylvan Lake, including units attractive to seasonal owners and investors. But a condo’s financing appeal depends on more than the unit itself.
Lenders may review:
- The corporation’s insurance
- Reserve fund strength
- Engineering reports
- Special assessments
- Litigation
- Building maintenance
- Short-term rental rules
- The percentage of investor-owned units
A condo building with insurance or reserve fund issues can be difficult to finance even when the individual unit is attractive.
5. Your first mortgage
The first mortgage balance and interest rate matter because they determine how much equity is left for a second mortgage.
A borrower with a large first mortgage, a high renewal rate, or substantial prepayment penalties may have less usable equity than expected.
Lenders may also want to know whether the first mortgage is current and whether there are other registrations on title.
6. Your situation and exit strategy
Credit and income still matter, but private lending is often more focused on the property and the plan to repay.
A lender may ask:
- Why is the money needed?
- How much monthly payment can you manage?
- Is the loan short-term or longer-term?
- Will you refinance with a bank later?
- Are you selling another property?
- Is a business, estate, separation, or debt restructuring involved?
A clear exit strategy can make a meaningful difference.
Sylvan Lake versus Calgary: a practical comparison
Location can influence lender appetite, but it is usually an indirect factor.
Calgary has a larger and more liquid resale market, with more standard detached homes and mainstream condo buildings. Sylvan Lake has strong demand, but the market includes more recreational, seasonal, investor, and short-term rental properties.
Here are three simplified examples:
| Borrower and property | Value | First mortgage | Proposed second | Combined LTV | Illustrative pricing range* |
|---|---|---|---|---|---|
| Sylvan Lake lakefront recreational property | $1,100,000 | $600,000 | $100,000 | 63.6% | Approximately 11.99%–13.99% |
| Sylvan Lake year-round in-town home | $420,000 | $220,000 | $60,000 | 66.7% | Approximately 10.99%–12.49% |
| Calgary standard residential property | $450,000 | $250,000 | $75,000 | 72.2% | Approximately 9.99%–11.49% |
*These are illustrative examples only, not quotes or guaranteed rates. Actual pricing depends on appraisal, lender, borrower profile, property use, fees, and exit strategy.
Notice what this table shows: the Calgary borrower has the highest CLTV, yet may still receive competitive pricing because the property is standard and highly marketable.
Meanwhile, the Sylvan Lake lakefront property has lower CLTV but may be priced higher because it is recreational and potentially more difficult to sell.
That is the key point: location matters, but property characteristics often matter more.
Worked example: a Sylvan Lake homeowner
Imagine a year-round Sylvan Lake homeowner with:
- Appraised value: $420,000
- First mortgage balance: $220,000
- Second mortgage: $60,000
- Combined LTV: 66.7%
- Illustrative interest rate: 11.49%
- Interest-only structure: 12 months
- Estimated lender fee: 3%
The monthly interest payment would be approximately:
$60,000 × 11.49% ÷ 12 = $574.50 per month
A 3% lender fee would be $1,800, before legal fees, appraisal costs, and any applicable brokerage fees.
The monthly payment looks manageable, but the homeowner must also plan for the $60,000 principal. The second mortgage may need to be:
- Paid out through a refinance
- Repaid from the sale of another property
- Cleared after a debt-consolidation plan
- Replaced with conventional financing after income or credit improves
The rate is only one part of the decision. The repayment plan is just as important.
When a second mortgage may be the wrong move
A second mortgage is not automatically the best way to access equity.
It may be the wrong move when:
- The payment is affordable only if everything goes perfectly
- The funds are being used to cover an ongoing monthly deficit
- There is no realistic exit strategy
- The property value is uncertain
- A sale would be more financially responsible
- The loan would only delay an unavoidable foreclosure
- The purpose is discretionary spending rather than solving a time-sensitive problem
For some homeowners, a conventional refinance, HELOC, sale, negotiated debt settlement, or financial counselling may be more appropriate.
At NOW Mortgage, the goal is not to force a private loan into every situation. The goal is to explain the available options clearly: including the cost.

When a second mortgage can make sense
A second mortgage may be worth exploring when you have meaningful equity and a defined use for the funds, such as:
- Debt consolidation
- Urgent repairs
- Business or investment needs
- A temporary income interruption
- A separation or spousal buyout
- Estate or probate-related expenses
- A short-term bridge before conventional refinancing
NOW Mortgage also works with Alberta homeowners looking at solutions such as a home equity loan in Alberta, mortgage for divorce settlement, and debt consolidation. Other specialized needs: such as agricultural financing in Alberta or a reverse mortgage for qualifying seniors: require a different analysis.
If your bank has declined you, that does not necessarily mean there are no options. It may simply mean the application does not fit that lender’s rules. Private lenders in Alberta may focus more heavily on equity, property value, and a credible repayment plan.
Sylvan Lake second-mortgage FAQ
Is a second mortgage in Sylvan Lake more expensive than one in Calgary?
Not automatically. A standard year-round Sylvan Lake home may receive similar pricing to a comparable Calgary property. Lakefront, seasonal, rural, condo, and short-term rental properties may receive higher pricing or lower LTV limits.
Can I get a second mortgage on a Sylvan Lake cottage?
Possibly, but the lender will likely review year-round access, servicing, heating, insurance, legal use, and resaleability. Seasonal properties are usually treated differently from primary residences.
Can I use short-term rental income to qualify?
Some lenders may consider rental income, but treatment varies. A short-term rental can be classified as an investment property, and income may be discounted or excluded if it is inconsistent or difficult to verify.
How much equity do I need?
There is no single answer. Many second-mortgage programs work within approximately 75% combined LTV, although the limit may be lower for condos, recreational properties, or smaller-market assets.
Do I need perfect credit?
No. Private lending may be available for borrowers with damaged credit, inconsistent income, or a recent bank decline. However, the property equity and repayment plan need to support the loan.
What should I prepare before applying?
Gather:
- Current first-mortgage statement
- Property tax information
- Income details
- Identification
- Appraisal or property information
- Details of any other liens
- The purpose of the loan
- Your intended exit strategy
You can start with the NOW Mortgage financing estimator, which does not require a credit check or obligation to review your potential options.
The bottom line
A second mortgage in Sylvan Lake is not priced simply because it is in Sylvan Lake.
A year-round in-town home may be treated much like a standard residential property in Calgary. A lakefront recreational home, a condo with building concerns, or a short-term rental property may face a very different lender response.
Before comparing rates, compare the full structure:
- Combined LTV
- Property classification
- Appraised value
- First-mortgage terms
- Interest and fees
- Monthly payment
- Exit strategy
For a confidential review, contact NOW Mortgage or read more about private mortgages. You can also call 587-200-6727 or email lending@nowmtg.ca.
Leave a Reply