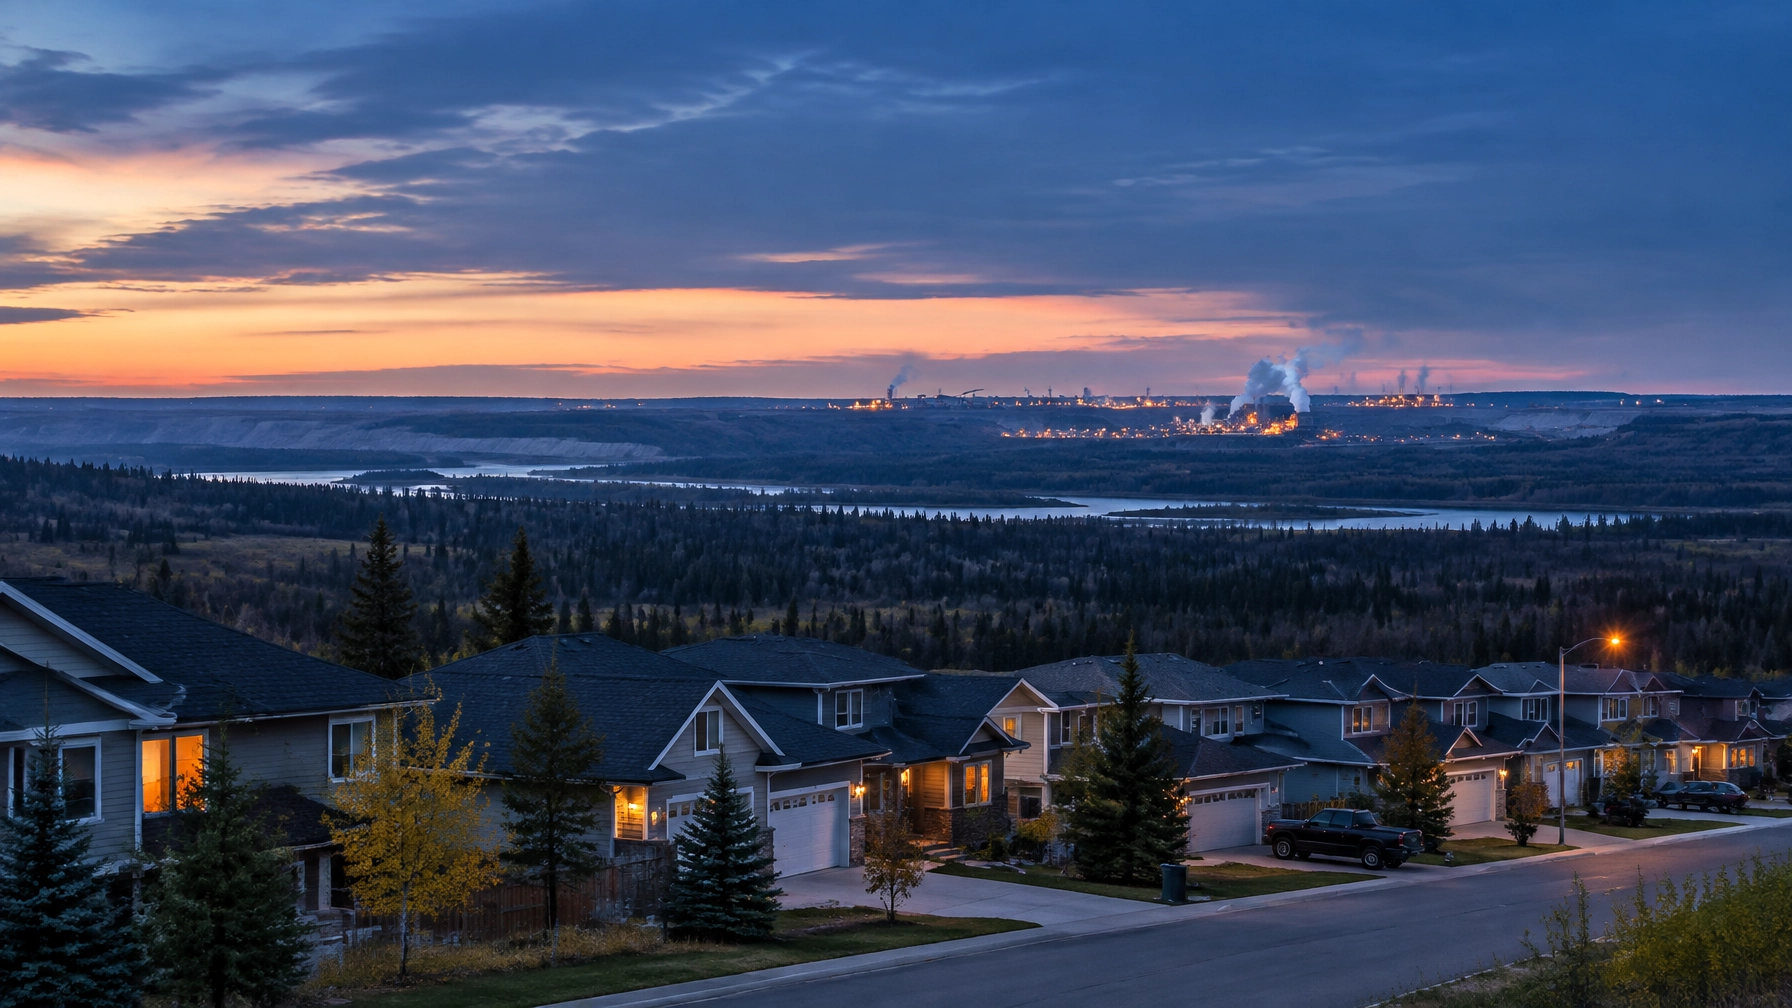
If you are researching a fort mcmurray private mortgage, here is what matters most before you apply.
Fort McMurray Private Mortgage at a Glance
- Used when a bank has declined a mortgage, refinance, or renewal application
- Approval is based mainly on property value and available equity, not credit score alone
- Funding can often be arranged in days rather than weeks
- Common uses include divorce buyouts, debt consolidation, and bridging a home sale
- Rates and fees are higher than a bank mortgage, so a clear exit plan matters
Fort McMurray Private Mortgage: What to Know
Fort McMurray is not an ordinary Alberta housing market.
As the urban service area of the Regional Municipality of Wood Buffalo, it is home to roughly 70,000 people and serves as the centre of Canada’s oil sands. Local incomes can be excellent, but they can also be highly cyclical. Rotation schedules, contractor work, shutdowns, camp pay, and oil-price swings can make a strong household look “unusual” on a bank application.
Then there are the property-specific challenges. The 2016 wildfire and 2020 flood still affect insurance availability, lender appetite, rebuilding records, and buyer confidence in some neighbourhoods.
So what happens when the bank says no, but you still have equity?
A private mortgage in Fort McMurray may provide a short-term bridge. It is not a cheaper replacement for a traditional mortgage. It is a flexible financing tool that can help you protect your home, consolidate debt, complete a buyout, or create time for a better long-term solution.
Why Fort McMurray borrowers get declined
A bank may decline a Fort McMurray homeowner for reasons that have little to do with the actual value of the property.
Common friction points include:
- Oil sands income is discounted: Banks may not count all overtime, bonuses, living-out allowances, camp pay, or rotational income.
- Contractor and owner-operator writeoffs: Your business may generate healthy cash flow, but tax deductions can reduce the income shown on your Notice of Assessment.
- Rotation schedules: A two-weeks-on, two-weeks-off schedule can look less predictable to an automated underwriting system.
- Past credit problems: Missed payments, a consumer proposal, bankruptcy, or high unsecured debt may block a conventional approval.
- Peak-market purchases: Some homes bought during an oil-price boom may no longer appraise high enough to support the current mortgage balance.
- Insurance complications: A lender may not advance funds if suitable property insurance is unavailable or if the home has unresolved wildfire or flood documentation.
Fort McMurray’s housing market can run hot and cold with the energy cycle. That matters when a borrower bought at the top of the market, needs to refinance, and discovers that the current appraisal does not match the old mortgage balance.
How a private mortgage looks at your file
Traditional banks focus heavily on income, credit score, debt ratios, and standardized employment history.
Private lenders in Alberta usually place more weight on:
- The property’s current market value
- Your available equity
- Property type and condition
- The requested loan-to-value ratio
- A realistic repayment or refinance plan
- Insurance and legal acceptability
At NOW Mortgage, financing may be available up to 75% loan-to-value, depending on the property type, location, condition, and overall strength of the application. That is not an automatic promise. A home in a standard, well-insured neighbourhood may receive different treatment from a flood-exposed property, acreage, rental, or property with a complex rebuild history.
You can also get started without a credit check to see what options may be available. A credit review and full underwriting may still be required before funding, but the initial conversation does not need to begin with a hard inquiry.

Wildfire, flood, and insurance are real lending issues
The 2016 Horse River wildfire destroyed or permanently damaged approximately 2,579 dwellings: about 10% of Fort McMurray’s housing stock, according to Regional Municipality of Wood Buffalo reporting.
The 2020 ice-jam flood affected more than 1,200 structures and required evacuations in areas including downtown Fort McMurray, Waterways, Draper, and Taiga Nova Industrial Park. RMWB’s flood-mitigation information also identifies ongoing planning considerations for areas such as Ptarmigan Court.
This history does not automatically make a property unfinanceable. It does mean the file may require more careful review.
A lender or insurer may ask for:
- Current home insurance confirmation
- Details of prior damage and remediation
- Rebuild permits or completion records
- An updated appraisal
- Flood-zone or municipal documentation
- Confirmation that the property is insurable on closing
In some cases, insurance availability affects approval outright. If the property cannot obtain suitable coverage, a lender may reduce the loan amount, require additional equity, increase pricing, or decline the application. That is not a technicality. It is one of the most important Fort McMurray-specific issues to address early.
What can a Fort McMurray private mortgage be used for?
Debt consolidation
High-interest credit cards, vehicle loans, tax arrears, and unsecured lines of credit can become especially difficult during a shutdown, layoff, separation, or project gap.
A home equity loan in Alberta may allow you to consolidate several payments into one mortgage-secured obligation. The numbers need to work, though. Consolidation only helps if you stop rebuilding the unsecured debt and have enough monthly breathing room to carry the new mortgage.
Divorce and separation buyouts
Rotational workforces and long periods away from home can add stress to an already difficult separation.
A mortgage for divorce settlement may help one spouse buy out the other, refinance the existing mortgage, or meet a court-ordered timeline. Private financing can be useful when income is temporarily reduced, documentation is incomplete, or the separation agreement is still being finalized.
NOW Mortgage also outlines divorce and separation financing options, including confidential handling and a planned transition back to traditional lending.
Estate settlements
An estate may contain a valuable Fort McMurray home but still lack enough liquid cash to pay taxes, beneficiaries, legal costs, or outstanding debts.
A short-term private mortgage can create time to sell the property properly instead of accepting a rushed offer. Estate and title issues must be reviewed carefully before any funds are advanced.
Acreage and agricultural financing
Properties outside the urban service area: including around Anzac, Saprae Creek, Gregoire Lake, and Fort McKay: may have different appraisal, access, servicing, and land-use considerations.
For agricultural or raw-land requests, NOW Mortgage’s agricultural financing information notes that financing is often considered up to 55% LTV, with higher leverage reviewed case by case. This is separate from standard residential lending and depends heavily on the land, use, location, and appraisal.
Reverse mortgages for seniors
Fort McMurray seniors may be asset-rich but income-constrained, particularly if their home has significant equity and their retirement income does not fit a bank’s refinance calculation.
A reverse mortgage can provide funds without the same type of required monthly mortgage payment, although the balance grows over time and the homeowner remains responsible for taxes, insurance, maintenance, and occupancy requirements. Read common reverse mortgage questions before deciding.
You may see this discussed online under searches such as reverse mortgage Edmonton, but the same suitability questions apply in Fort McMurray.

Bank versus private lender: how long can it take?
The exact timeline depends on the property and paperwork, but the process often looks like this:
| Stage | Traditional bank | Private lender |
|---|---|---|
| Initial review | Several business days to weeks | Often same day or within a few days |
| Income verification | Detailed and standardized | More flexible documentation |
| Appraisal and property review | Required in many cases | Usually required, with equity emphasis |
| Approval | May take weeks if escalated | Potentially days after a complete file |
| Closing | Often 2–6 weeks | Can be faster when legal and insurance items are ready |
Fast funding is helpful, but speed should not replace due diligence. You still need to understand the rate, lender fee, legal fees, appraisal cost, term, payout conditions, and renewal expectations.
The most important part: your exit strategy
Private lending is usually a short-term bridge, not a forever mortgage.
Rates and fees are generally higher than a bank mortgage. Terms are often shorter, commonly one or two years. Before committing, ask:
- What income will a future lender need to see?
- Will my credit improve through on-time payments?
- Can I reduce unsecured debt?
- Will my property appraisal support the refinance?
- Is the home currently insurable?
- What happens if oil prices fall or my contract ends?
- Do I have enough time to refinance before the private term expires?
A good exit strategy may involve returning to an A-lender, moving to a B-lender, selling the property, or paying out the loan from another source. If there is no credible exit plan, the loan may simply delay the problem.
NOW Mortgage provides pre-qualification and financing estimates so you can begin with the property, mortgage balance, income situation, and funding goal: not just a credit score.
Fort McMurray private mortgage FAQ
Can I get a private mortgage with bad credit?+
Possibly. Private lenders focus more on equity and property value than traditional lenders do, but bad credit still affects the risk assessment and pricing. The reason for the credit issue, current payment history, and available equity all matter.
Can I qualify with rotational oil sands income?+
Possibly. A lender may review pay stubs, employment letters, contracts, bank statements, T4s, tax returns, and work history. Private financing can be more flexible when a bank discounts rotation pay, overtime, or living-out allowances.
Can I finance a home affected by wildfire or flood?+
Possibly, but insurance and documentation are critical. A property with unresolved damage, incomplete rebuilding records, or limited insurance options may receive a lower LTV, higher cost, or no approval.
Is a private mortgage the same as a second mortgage?+
No. A private mortgage can be a first mortgage or a second mortgage. A second mortgage sits behind the existing first mortgage and is usually priced higher because the second lender is paid after the first lender if the property is sold.
What if I searched for private mortgage Edmonton, private mortgage Calgary, or bad credit mortgage Calgary?+
Those searches may bring up Alberta-wide options, but Fort McMurray requires local consideration of oil-sands income, cyclical values, insurance, wildfire, flood exposure, and outlying property types. The same applies when comparing a second mortgage Calgary option or a debt consolidation mortgage Edmonton strategy.
How do I compare the total cost?+
Request a written estimate showing all fees before committing, including interest, lender fees, legal costs, appraisal charges, broker compensation where applicable, and payout terms. At NOW Mortgage, upfront cost clarity is part of the process.

Start with a clear answer, not another blind application
A bank decline can feel final. In Fort McMurray, it may simply mean the lender could not fit your income, property, insurance, or timing into its standard rules.
A private mortgage may provide a workable bridge: but only when the equity, affordability, costs, and exit plan make sense.
Whether you first found us while searching private lenders Alberta, agricultural financing Alberta, or a home equity loan Alberta, the next step is the same: review the full picture before making a decision.
Start a confidential conversation with NOW Mortgage. No credit check is required to get started, and you will receive a clear explanation of the available options and estimated costs before committing.
Leave a Reply