A bank decline can feel especially frustrating in Drumheller.
You may own a home in the Red Deer River valley, have substantial equity, and still be told that your income, credit history, property condition, or documentation does not fit the bank’s rules.
That does not automatically mean selling your home.
A private mortgage in Drumheller can provide a short-term bridge when traditional financing is unavailable, but Drumheller properties require more careful review than a standard urban home in Calgary or Edmonton.
Why Drumheller properties can be harder for banks to finance
Drumheller is a community of roughly 8,000 people in Alberta’s Badlands, about an hour and a half northeast of Calgary. Its economy is connected to tourism, the Royal Tyrrell Museum, agriculture, oil and gas, construction, and regional services.
Its housing market is also distinctly local.
The valley contains older homes, former mining areas, modest-priced properties, and neighbourhoods with different elevations and ground conditions. Homes on surrounding prairie land can have a very different risk profile from properties closer to the river.
A bank may hesitate because of:
- Coal-mine undermining or subsidence concerns
- Floodway, flood fringe, or overland-flow exposure
- Older foundations, roofs, wiring, plumbing, or heating systems
- Seasonal tourism or contract income
- Farm and ranch income that is difficult to document through standard pay stubs
- A paid-off home owned by a senior with limited qualifying income
- A low property value that leaves too little equity after existing debt and costs
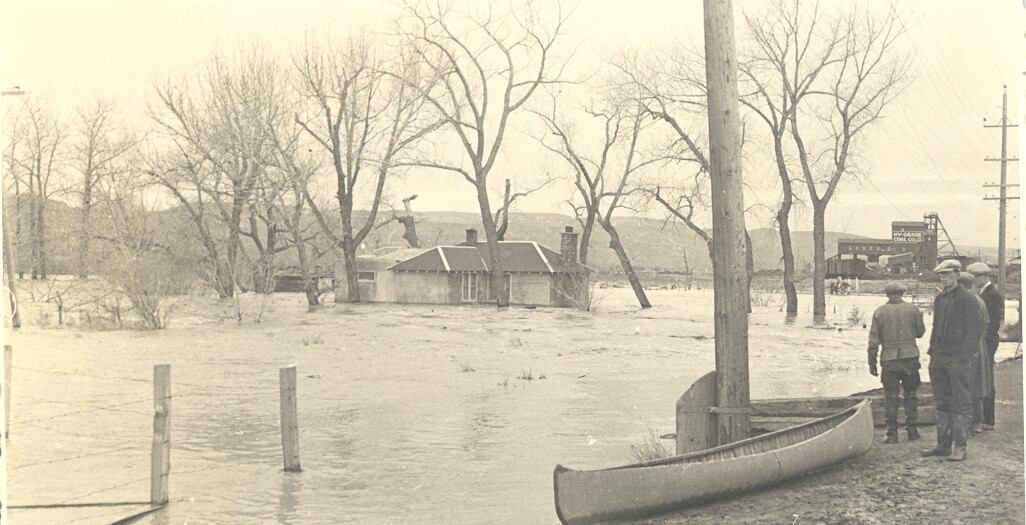
Drumheller’s own Flood Resiliency Program identifies a long history of flooding, including the major 2013 event. The Town is continuing work involving berms, mapping, preparedness, and floodway buyouts.
The point is not that every Drumheller home is risky. It is that the specific property matters.
Mine subsidence and flood exposure affect lender appetite
A lender will want to know more than the municipal address.
For a valley property, the review may include:
- Whether the home is in a floodway, flood fringe, or outside mapped flood-risk areas
- Whether floodproofing or rebuilding restrictions apply
- The property’s elevation and proximity to the Red Deer River or tributaries
- Any history of basement seepage, foundation movement, or insurance claims
- Whether the lot is in an area affected by historic coal mining
- Whether a current appraisal can support the requested loan amount
The Town’s flood maps and berm information are useful starting points. You should also ask your real estate professional, insurer, municipality, and lender for property-specific information.
A private lender may be more flexible than a bank, but flexibility does not mean ignoring risk. A property in a high-risk flood area or an undermining zone may receive a lower loan-to-value limit, require additional documentation, or be declined altogether.
Older homes may have equity, but not enough qualifying value
Drumheller’s affordability is a major advantage for homeowners. It can also create a financing challenge.
A home worth less than a comparable Calgary property may have a strong percentage of equity but limited absolute equity. Appraisal fees, legal costs, lender fees, and interest can consume a meaningful part of a smaller loan.
For example, if a property’s value is modest and an existing mortgage already uses most of the available lending room, a second mortgage may produce only a small net advance. In that situation, the financing may not be practical.
That is why you should ask for:
- The estimated property value
- The maximum loan amount
- The existing mortgage payout
- All lender, broker, legal, appraisal, and discharge costs
- The actual net amount you receive
- The expected monthly payment
- The plan for paying out the private mortgage
At NOW Mortgage, the goal is to provide an upfront estimate of the costs before you commit, not a vague promise that becomes expensive at closing.

How much can you borrow?
For some standard residential properties, private mortgage financing may be available up to 75% loan-to-value, depending on the property type, location, condition, appraisal, and overall file.
That is a maximum guideline, not a guarantee.
A lender may use a lower LTV for:
- Rural or acreage properties
- Homes with significant deferred maintenance
- Properties affected by flood exposure
- Homes with possible mine-subsidence concerns
- Older properties with limited comparable sales
- Non-standard construction
- Properties that are difficult to insure or resell
Farm and raw-land financing is assessed differently from residential lending. NOW Mortgage’s agricultural financing information notes that many farm and raw-land files are considered around 55% LTV, with higher leverage only in exceptional cases.
For Starland County and Kneehill County farm, ranch, and acreage owners, the property may be valuable, but land use, improvements, access, income, and marketability all affect the lending decision.
When a private mortgage may help Drumheller homeowners
A private mortgage is usually a short-term solution, not a replacement for a conventional bank mortgage.
Common uses include:
Debt consolidation
High-interest credit cards, tax arrears, personal loans, and other debts can become difficult to manage. A home equity loan in Alberta may consolidate several payments into one mortgage-secured structure.
The key is using the breathing room to create a longer-term plan. Consolidating debt without changing the underlying problem can simply postpone the pressure.
Divorce or separation buyouts
A separation may require one spouse to refinance, remove the other spouse from title, or buy out their share of the home.
Traditional lenders may not move quickly enough when agreements, court dates, or refinancing deadlines are involved. NOW Mortgage provides divorce and separation financing for situations such as spousal buyouts, title changes, and interim funding.
This is often searched as a mortgage for divorce settlement. In practice, the lender will still need the property value, existing debt, and a clear repayment or refinancing plan.
Estate and probate settlements
An estate may own a Drumheller home with unpaid taxes, repairs, mortgages, or multiple beneficiaries. A short-term private mortgage can sometimes provide funds while probate, a sale, or a beneficiary buyout is being completed.
The executor should obtain legal advice before pledging estate property.
Agricultural financing
Farm and acreage owners around Drumheller may need funds for equipment, repairs, operating costs, land improvements, or a transition between ownership generations.
Agricultural income can be seasonal and uneven, which may not fit a bank’s standard income model. Agricultural financing in Alberta still requires a realistic assessment of the land, improvements, debt, and exit strategy.

Reverse mortgages for Drumheller seniors
Drumheller has a significant senior population, including long-tenure homeowners who may own a home outright but have limited verifiable income.
A reverse mortgage or other equity-based solution may help with:
- Monthly cash flow
- Home repairs
- Medical or accessibility expenses
- Paying off high-interest debt
- Helping family members
- Staying in the home longer
A reverse mortgage is not free money. Interest increases the balance, and the loan is generally repaid when the home is sold or the borrower permanently leaves. Taxes, insurance, and maintenance must remain current.
See NOW Mortgage’s guide to reverse mortgage questions before making a decision.

Bank versus private lender: a realistic timeline
The right timeline depends on the file, but the difference can be significant.
| Stage | Traditional bank | Private lender |
|---|---|---|
| Initial review | Several business days to weeks | Often same day or within a few days |
| Income and credit review | Detailed and standardized | More focused on equity, property, and plan |
| Property appraisal | Often required | Usually required, especially for non-standard property |
| Approval | May take weeks | Can be much faster if documents are ready |
| Funding | Often weeks after application | Sometimes days after approval and legal instructions |
| Best fit | Long-term financing | Short-term bridge or urgent restructuring |
“No credit check” generally means no credit check is required to get started and see your options. A lender may still review credit before funding, particularly when setting terms and confirming the full risk picture.
What to prepare before applying
To make a Drumheller application easier, gather:
- Property address and legal description, if available
- Current mortgage and secured debt balances
- Recent property tax information
- Income documents or an explanation of self-employed, farm, or tourism income
- Details of any flood, foundation, or insurance issues
- Separation agreements, probate documents, or court deadlines where applicable
- A clear explanation of how the loan will be repaid
You can begin with the NOW Mortgage financing estimator. There is no credit check or obligation required to start.
FAQs about private mortgages in Drumheller
Can I get a private mortgage if my credit is poor?
Possibly. Private lending is usually driven more by the property’s value and available equity than a bank mortgage. However, poor credit can still affect pricing, approval, and the required exit plan.
Can a Drumheller home in a flood-risk area qualify?
Possibly, but the flood designation, insurance availability, condition, location, and marketability will matter. Some properties may receive a lower LTV or may not qualify.
Can I borrow up to 75% of my property value?
Up to 75% may be possible for certain residential properties. Rural, older, flood-exposed, undermined, or non-standard properties may qualify for less.
Is a private mortgage more expensive than a bank mortgage?
Usually, yes. Private mortgages generally have higher interest rates and fees because they address situations with greater complexity or risk. They should be treated as a bridge, with a defined plan to refinance, sell, or repay.
How do I know whether a second mortgage is worthwhile?
Ask for the net proceeds after every cost. In a lower-value market such as Drumheller, a second mortgage may not make sense if the amount left after existing debt and fees is too small to solve the problem.
Can I use private financing for a separation or estate settlement?
Often, yes. The lender will need the property details, existing debt, legal documents, and a clear understanding of who can authorize the mortgage.
The bottom line
A bank decline is not the end of the conversation: but it is a signal to look closely at the property and the plan.
For Drumheller homeowners, that means addressing flood exposure, coal-mine undermining, older construction, insurance, modest property values, and income that may come from tourism, farming, contracting, or retirement rather than a conventional paycheque.
NOW Mortgage provides transparent cost estimates, flexible lending criteria, fast decisions, and no credit check required to get started. Start with the numbers, understand the net amount, and make sure the private mortgage has a realistic exit.
Start a confidential application with NOW Mortgage or contact the Alberta lending team at lending@nowmtg.ca.
Leave a Reply