If you are looking for a second mortgage in Drumheller, you may wonder whether living outside Calgary automatically means a higher rate.
The short answer is: location matters, but the property matters more.
A $230,000 valley home in Drumheller, a $600,000 acreage in Starland County, and a $450,000 home in Calgary can all receive very different mortgage terms. The town boundary is only one piece of the lending decision.
For private lenders in Alberta, the bigger questions are usually:
- How much equity is available?
- What is the combined loan-to-value ratio?
- Is the property easy to resell?
- Can it be insured?
- What is the borrower’s repayment or refinance plan?
Drumheller is a unique market. The town of roughly 8,000 sits in the Red Deer River valley, surrounded by Badlands scenery, dinosaur tourism, agriculture, and a history tied to coal mining. The Royal Tyrrell Museum draws visitors from across the country, while local income may come from tourism, farming, oil and gas, trades, health care, and small business.
That mix creates opportunity: but also property-specific lending questions.
What a second mortgage actually looks at
A second mortgage is registered behind your existing first mortgage. The lender is taking additional security in the equity left after the first mortgage is paid out.
The basic calculation is:
Combined LTV = first mortgage + second mortgage ÷ appraised property value
The lower the combined LTV, the more protection the lender generally has if the property must be sold.
A lender will also review:
- The first mortgage balance and interest rate
- Property condition and required repairs
- Appraised value and recent comparable sales
- Property type and zoning
- Insurance availability
- Borrower income, credit, and overall situation
- The proposed exit strategy
Credit still matters, but private lending is often more focused on the property and the plan than a bank application is. That is why homeowners searching for a bad credit mortgage Calgary or a private mortgage Edmonton may still have options if they have usable equity and a realistic way to repay.
Drumheller’s location-specific lending realities
Drumheller is not one uniform real estate market.
A home near the valley floor may have a very different risk profile from a prairie-facing property on higher ground: even if both are inside the same municipality.
Flood exposure and insurance
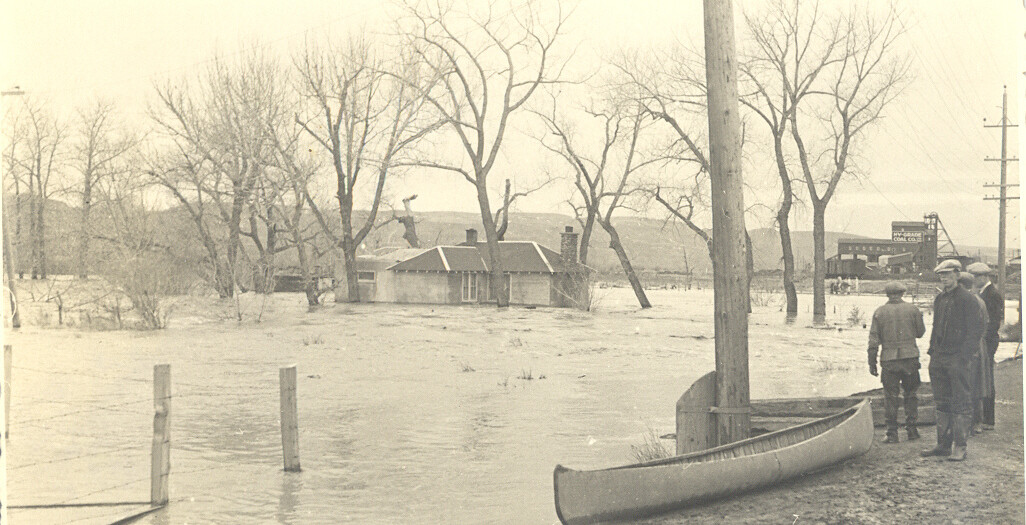
The Red Deer River and surrounding waterways are a real part of Drumheller’s history. The Town identifies major flood events in 1915, 1931, 1948, 1954, 1997, 2005, 2013, and 2018.
The Town’s Flood Resiliency Program includes berm construction, upgrades, floodway buyouts, education, and emergency preparedness. Alberta’s Drumheller flood study assesses river-related hazards along the Red Deer River, Kneehills Creek, Michichi Creek, Rosebud River, and Willow Creek.
That does not mean every Drumheller property is unfinanceable. It does mean a lender may ask more questions about:
- Flood-zone mapping
- Past water damage or insurance claims
- Overland flood and sewer-backup coverage
- Basement seepage and drainage systems
- Elevation and access
- Whether insurance is available at a reasonable cost
Insurance is important because a property that cannot be adequately insured may be difficult for a lender to accept as collateral.
Former mine sites and subsidence history
Drumheller’s coal-mining past is another consideration. Some properties sit in areas affected by former mine workings or historic subsurface activity.
That does not automatically reduce a property’s value. However, an appraiser, insurer, lawyer, or lender may want more information about:
- Mine-site history
- Previous structural movement
- Foundation repairs
- Geotechnical or engineering reports
- Municipal records and disclosure documents
This is one reason property risk can matter more than equity. A homeowner may have substantial paper equity, but the lender still needs confidence that the property is stable, insurable, and saleable.
Side-by-side: Drumheller, Starland County, and Calgary
The following examples are illustrative only. They are not rate quotes or approvals.
| Example | Property value | First mortgage | Requested second | Combined LTV | Main lending question |
|---|---|---|---|---|---|
| Drumheller valley home | $230,000 | $135,000 | $20,000 | 67.4% | Flood exposure, insurance, mine history, resale value |
| Starland County acreage | $600,000 | $300,000 | $60,000 | 60.0% | Agricultural use, appraisal support, access and buildings |
| Calgary residential property | $450,000 | $300,000 | $60,000 | 80.0% | Higher leverage, payment capacity, neighbourhood resaleability |
The Calgary property may look easier because Calgary has a deeper resale market. But its 80% combined LTV gives the lender less protection than the Drumheller valley example at 67.4%.
Meanwhile, the Starland County acreage has the strongest equity position in this comparison, but rural and agricultural properties can require more specialized underwriting.
For agricultural financing Alberta borrowers, land use, outbuildings, road access, water systems, zoning, and income from the property may all affect the appraisal. NOW Mortgage publishes separate agricultural and raw-land guidelines, including lending up to 55% LTV in many cases. That guideline is for that type of financing and should not be treated as an automatic second-mortgage approval.
Worked example: a $230,000 Drumheller home
Suppose a homeowner owns a valley property appraised at $230,000.
- Existing first mortgage: $135,000
- Requested second mortgage: $20,000
- Total registered mortgage debt: $155,000
- Gross equity before transaction costs: $95,000
- Combined LTV: $155,000 ÷ $230,000 = 67.4%
For simple illustration, assume the second mortgage rate is 10% annually and the loan is interest-only.
- Annual interest: $2,000
- Approximate monthly interest: $166.67
If an illustrative 2% lender fee applied, that would be another $400. Legal, appraisal, registration, and other costs may also apply. Actual pricing and fees must be provided for the specific file before commitment.
The important point is not the assumed rate. It is the structure.
At 67.4% combined LTV, the loan may look reasonable from an equity perspective. But the final terms could still be affected by flood exposure, insurance restrictions, property condition, or the borrower’s exit plan.
A prairie property in Drumheller with the same value and mortgage balances might receive different consideration if it has stronger resaleability and fewer flood or subsidence concerns.
Why Calgary is not automatically cheaper
Calgary usually offers a broader pool of buyers, more comparable sales, and more standardized residential housing. Those factors can help with appraisal and resaleability.
But Calgary properties can still face challenges, especially in floodway or flood-fringe areas along the Bow and Elbow Rivers. The City’s Regulatory Flood Map should be reviewed during property due diligence.
A second mortgage Calgary homeowner may also be dealing with:
- A high first-mortgage balance
- Expensive consumer debt
- A variable or irregular income
- A divorce or separation
- A recent job change
- A property requiring repairs
So while a Calgary property may be easier to sell, a high combined LTV or weak exit plan can still result in difficult terms.
In other words, Calgary does not guarantee a lower rate, and Drumheller does not guarantee a higher one.
When a second mortgage is the wrong move
Here is the blunt version: a second mortgage is not a magic reset button.
It may be the wrong move if:
- You are borrowing to cover an ongoing monthly shortfall with no change in sight.
- The payment will make your budget worse rather than better.
- You have no credible plan to refinance, sell, or repay.
- The property has serious insurance, structural, or title concerns.
- You are using short-term financing for a long-term problem.
- The loan only delays an unavoidable sale.
- The first mortgage has penalties or restrictions that make the structure too expensive.
- You are consolidating debt but planning to immediately run the balances back up.
A second mortgage can be useful for a defined problem: such as debt consolidation, a time-sensitive mortgage for divorce settlement, or bridging a temporary income disruption. It should not be used simply because the equity is available.
Common uses for Alberta homeowners
Homeowners may investigate a second mortgage or private refinance for:
- Debt consolidation
- A spousal buyout
- Estate or probate-related expenses
- Business or agricultural working capital
- Repairs before selling
- A mortgage renewal that was declined
- Short-term financing while income stabilizes
NOW Mortgage also works with other equity-based situations, including divorce and separation financing, private mortgages, and farm and raw land financing.
Depending on the borrower’s age and goals, alternatives may include a home equity loan Alberta, a conventional refinance, or a reverse mortgage Edmonton solution. Each has different qualification rules, costs, repayment expectations, and long-term consequences.
Drumheller second-mortgage FAQ
Does living in Drumheller automatically mean a higher rate?
No. Drumheller’s smaller market and property risks can affect pricing, but the lender will also consider LTV, insurance, appraisal quality, property condition, and the exit strategy.
Are valley properties impossible to finance?
No. They may require more due diligence. Flood mapping, insurance availability, past claims, drainage, basement systems, and any mine-related information can all matter.
Can I get a second mortgage with bad credit?
Possibly. Private lenders may focus more heavily on equity and the property than a bank does, but poor credit can still affect pricing, documentation, and approval.
Can an acreage near Drumheller qualify?
Potentially. An acreage in Starland or Kneehill County may require specialized appraisal work, especially where there is agricultural use, outbuildings, raw land, wells, septic systems, or mixed residential and farm activity.
Do I need legal advice?
You should consider independent legal advice before signing. This article is general information, not legal, tax, insurance, or financial advice. Your own lawyer, insurer, and qualified professionals should review the property and transaction.
What should I prepare before applying?
Start with:
- Current first-mortgage statement
- Property tax information
- Insurance details
- Income and debt information
- Recent appraisal or comparable information, if available
- A clear explanation of how the funds will be used
- A realistic repayment or refinance plan
The bottom line
Does location change your second-mortgage rate?
Sometimes: but the specific property usually matters more than the municipality.
A $230,000 Drumheller valley home may have affordable pricing but limited absolute equity and additional flood or subsidence questions. A $600,000 Starland County acreage may have stronger equity but more complex agricultural underwriting. A $450,000 Calgary home may have better resale liquidity but a higher combined LTV.
The best next step is a transparent review of the full file: not a rate guess based on the town name.
NOW Mortgage provides upfront cost estimates, flexible lending options, and no credit check required to start exploring what may be available. Start a confidential conversation before committing to a second mortgage.
Leave a Reply